The Name on the Entry: Assigning Importer-of-Record Status Before UK Goods Reach New Europe
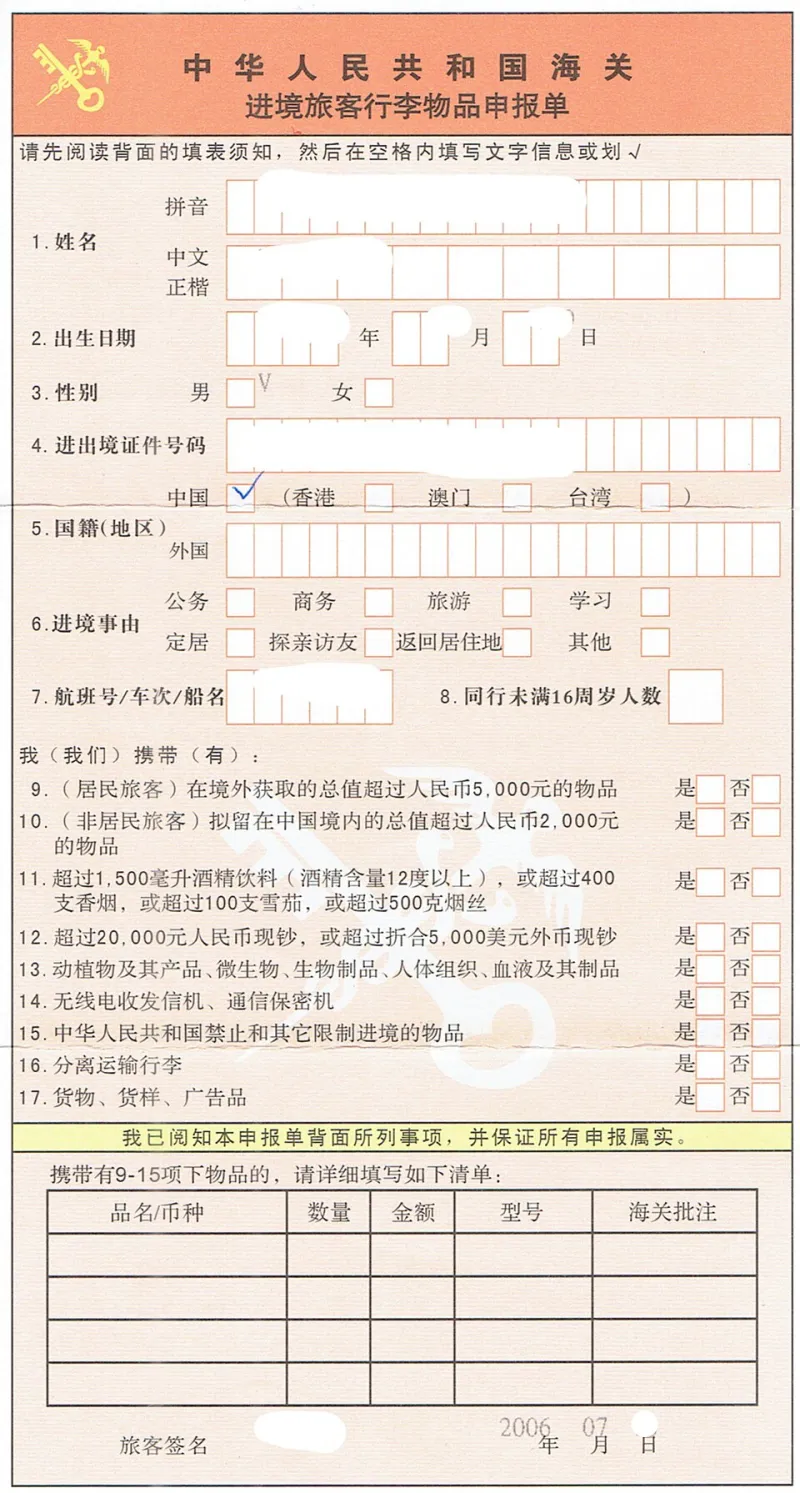
Photo: Unknown authorUnknown author, Public domain, via Wikimedia Commons
UK exporters entering Serbia, Romania, Moldova, Albania or Ukraine often focus on price, logistics and the first order. The customs entry can feel like a downstream detail. In practice, the name that appears as importer of record on that entry determines who carries many of the obligations that follow the goods: duty and tax liabilities, product-compliance duties, record-keeping, and responsibility when something must be withdrawn or recalled.
That name should not be discovered after the container has arrived. It should be written into the commercial relationship before dispatch.
The role is legal, not logistical
Importer-of-record status is not simply a description of who arranged the shipment. It identifies the party legally responsible for bringing goods into the destination market and for meeting the associated customs and regulatory requirements. The precise test varies by country, but the practical consequence is consistent: the importer is the party the authorities will pursue for declarations, duties, taxes and compliance evidence.
For a UK exporter, the risk is not only that a local partner becomes the importer by accident. It is also that the partner is assumed to be the importer when, in law or in practice, it has not accepted the role. A distributor may market the goods, hold stock and invoice customers while remaining merely a buyer. A fulfilment provider may handle warehousing without taking on customs liability. An agent may sign documents without having authority to act as importer. These distinctions matter when a shipment is halted, a product is challenged or a recall is ordered.
How the role drifts
The shift is rarely announced. It happens through routine arrangements.
A UK business sells on delivered terms and assumes the buyer is the importer, but the buyer has not registered for the relevant local tax or customs mechanism. A fulfilment partner clears goods in its own name to keep the operation moving. A local agent signs a customs declaration as a representative without a written mandate that clarifies whether it acts in its own name or on behalf of the exporter. Consignment stock is moved into a warehouse before a local entity has been appointed. In each case, the importer-of-record position may be unclear at exactly the moment clarity is most valuable.
The first shipment is a poor time to resolve this. Border officials work from the declaration and the supporting documents, not from the spirit of the distribution agreement. If those documents name one party while the contract implies another, the exporter may face delays, unexpected tax demands or difficulty enforcing an indemnity.
Incoterms do not decide the importer
Incoterms are useful for allocating transport costs, risk and some delivery obligations. They are not a substitute for identifying the importer of record. A DAP or DDP term may tell the parties who pays for carriage or clearance, but it does not by itself establish which legal person is the importer in the destination country. Nor does it resolve who holds the product-compliance file, who is responsible for labelling, or who must act if a recall is required.
UK exporters should treat the Incoterm as one clause among several. The contract also needs an express importer appointment, a statement of responsibilities, and a mechanism for resolving gaps. Where a local entity is to act as importer, the agreement should say so directly and should require the entity to maintain the necessary registrations and authorisations.
Country practicalities, one principle
Romania, as an EU member, applies EU customs and product rules, but the importer must still be correctly identified and registered for the relevant tax and customs processes. Serbia, Moldova, Albania and Ukraine each have their own customs procedures, registration requirements and local representation rules. The details differ; the principle does not. A UK exporter should obtain local confirmation of who can act as importer, what registrations are required, and what documents the customs authority will expect to see.
In Ukraine, reconstruction-related demand and ongoing wartime administrative arrangements make documentary precision especially important. In the Western Balkans, smaller distribution networks can mean the same local company acts as buyer, warehouse keeper and customs declarant. That concentration of roles increases convenience but also increases the need for written allocation of liability.
Contract clauses that assign the role
A deliberate importer-of-record clause should do more than name a party. It should allocate the obligations that travel with the role. UK exporters should consider provisions covering:
- Express appointment of the importer, identified by legal name and registration number.
- The importer's responsibility for customs declarations, duty, VAT and other local taxes.
- Product-compliance obligations, including technical files, labelling, language requirements and safety documentation.
- Record-keeping and cooperation with audits or inspections.
- Recall and withdrawal procedures, including who funds and manages corrective action.
- Indemnities that survive termination and cover historic entries.
- A requirement to notify the exporter before changing importer status or customs representation.
- Clear authority for any agent or representative acting on the importer's behalf.
The clause should be mirrored in the commercial documents. A distribution agreement that appoints an importer is weakened if the invoice, packing list and customs instruction name a different party.
Documentation checklist before first shipment
Before goods leave the UK, the exporter should hold a file that answers the importer question conclusively. It should include:
- A signed contract or side letter expressly appointing the importer of record.
- Confirmation of the importer's local registration and customs identification.
- A written customs representation mandate where an agent is used.
- The agreed Incoterm and a note explaining that it does not determine importer status.
- Product-compliance evidence matched to the destination market.
- Labelling and language specifications agreed with the importer.
- A recall and incident-response contact sheet.
- A named person at the exporter responsible for approving importer changes.
- Copies of the first customs entry and supporting documents after clearance.
- A review date for the arrangement, particularly where volumes or product lines are changing.
Make the name deliberate
The importer of record is not a clerical detail. It is a liability allocation. UK exporters selling into Europe's newer markets should decide who holds that role, write it into the contract, align the customs documentation, and check that the chosen party has the registrations and capacity to perform. If the name on the entry is not the name the contract intended, the exporter has left liability to chance.